Health · For freelancers
Choosing the Best Health Plan as a Freelancer: ACA vs. Private Compared
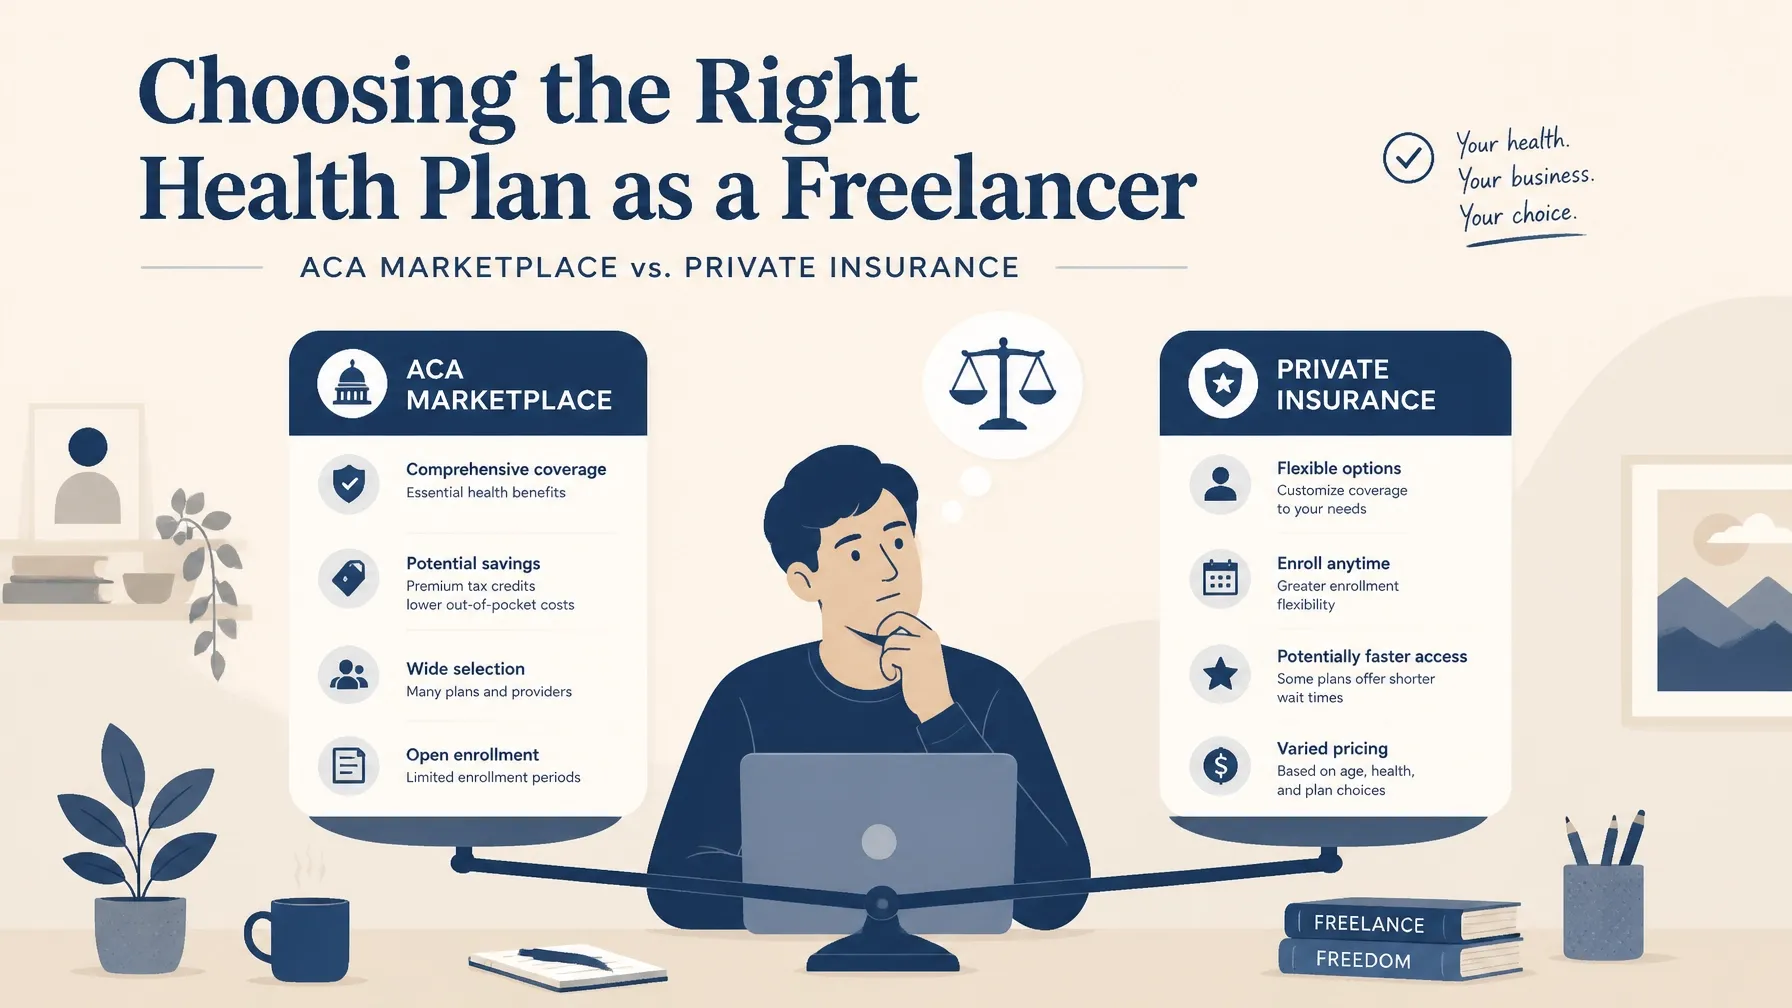
When you work for yourself, no employer hands you a health plan — the decision is entirely yours. That freedom is one of the best parts of freelancing, but it also means you’re the one weighing cost, coverage, and networks. Most self-employed people land on one of two paths: a plan from the ACA Marketplace, or a private plan bought directly from an insurer. Here’s how the two compare, and how I help my freelance clients choose.
What you’re actually choosing between
Both options are real, comprehensive health insurance. The difference is mostly aboutwhere you buy the plan and whether you can get help paying for it. Get that framing right and the “best” plan usually becomes clear.
Option 1 — ACA Marketplace plans
These are sold through the Health Insurance Marketplace. For freelancers, their biggest draw is help with the cost:
- Income-based premium tax credits can lower your monthly cost — and because freelance income is often uneven, this is where many self-employed clients find real savings.
- Guaranteed issue: you can’t be turned down or charged more for a pre-existing condition.
- Every plan covers the essential health benefits and is sorted into Bronze, Silver, Gold, and Platinum tiers, so you can trade premium for out-of-pocket cost.
- Lower earners may qualify for extra cost-sharing help on Silver plans.
Option 2 — Private plans bought directly
Private plans are purchased straight from an insurance company or through a licensed agent, off the Marketplace. You won’t get the ACA subsidies here, so you pay full price — but if your income is too high to qualify for a subsidy anyway, a private plan can offer more choices and, sometimes, different network options.
One caution I always share: not everything sold “off-exchange” is full major-medical coverage. Short-term and limited plans can look cheap but may exclude pre-existing conditions or cap what they pay. I make sure you know exactly what you’re buying before you commit.
How I help you decide
- Estimate your annual income first — it drives whether a subsidized Marketplace plan or a private plan is the better deal.
- Check your doctors and prescriptions against each plan’s network and drug list before you enroll.
- Match the metal tier and deductible to how often you actually expect to use care.
- Consider an HSA-eligible high-deductible plan if you want a tax-advantaged way to save.
- Mind the calendar — outside Open Enrollment you generally need a qualifying life event to switch.
There’s no single “best” plan — only the best plan for your income, your health, and your budget. As an independent agent, I compare both Marketplace and private options across many top-rated carriers and translate the fine print into plain English, so you can choose with confidence.
Not sure which path fits your freelance income?
Let’s look at your numbers together. I’ll check your subsidy eligibility and compare Marketplace and private plans side by side — free, and with no obligation.
Prefer to talk? Call919-353-2500. Sandra Wester · Inspired Insurance Solutions · NPN 21768120.
This article is for general education only. It is not a guarantee of coverage or benefits. Plans, prices, and rules vary. Read your official plan documents before you enroll.
Back to all insights